



No, you generally can’t get a standard title loan on a leased car. The leasing company holds the title, not you, and a title loan requires a clean title in your name so we can place a lien on it.
The one exception is a lease buyout: paying off the lease to take ownership first, then using the vehicle to secure a title loan.
A lease buyout involves real costs, and it’s worth running the numbers before you apply. Below, we explain why leasing works differently than owning, what a buyout typically costs, and how to tell whether it actually closes your financial gap.
You can fill out our online loan request to see how much you may qualify for and check if you’re eligible for a title loan or other loan options, with no obligation.
The One Exception: A Lease Buyout
Leasing and owning are different ownership situations. A leased car’s title belongs to the leasing company.
Only once you buy out the lease and the title transfers into your name can we place a lien on it for a title loan. That buyout is the only path from a leased vehicle to a title loan.
Quick Facts
- You can’t use a leased car as collateral for a standard title loan because the leasing company holds the title, not you.
- A lease buyout transfers the title into your name, which is what then makes a title loan possible.
- A buyout price typically includes the car’s residual value, any remaining lease payments, contractual fees, and applicable sales tax.
- We review your vehicle’s value alongside your ability to repay and state law to set a loan amount, rather than lending a fixed percentage of the car’s value, so it’s worth comparing that figure to your buyout price before committing.
- A leased car and a financed car are different situations. If your car is financed rather than leased, see our guide to a title loan on a financed car.
Editorial Disclosure: Montana Capital Car Title Loans® (NMLS ID 2249848) is a licensed direct lender. This content is informational only and does not offer legal or financial advice. Terms, APRs, and availability may vary by state and borrower qualifications.
Can You Get a Title Loan on a Leased Car?
You generally can’t get a standard title loan on a leased car, because the leasing company holds the title, not you. A title loan requires a clean title in your name so we can place a lien on it.
A lease doesn’t give you that. The leasing company is functionally the owner during the lease term; you’re paying to use the car, not to own it, which is exactly what a title loan requires.
For example, if Alex leases a Honda Civic, he can’t use it to get a title loan because the leasing company holds the title. This is the standard case. There’s one conditional exception, covered next.
Why Doesn’t a Lease Qualify the Same Way an Owned Car Does?
Leasing, financing, and owning outright are three different ownership situations, and only one of them gives you a title to use as collateral. A financed car already has your name on the title, just with a lien attached. A leased car doesn’t have your name on the title at all, which is the real difference that matters here.
| Leased | Financed | Owned Outright | |
| Who holds the title | The leasing company | You, with a lien | You, free and clear |
| Standard title loan possible? | No | Yes | Yes |
| What changes that | Buying out the lease to take ownership | Usually, nothing extra is needed | N/A |
What Is a Lease Buyout, and How Does It Work?
A lease buyout means paying off your lease early to take ownership of the car. Once that happens, the title transfers to you, and a title loan becomes possible.
Montana Capital Car Title Loans® Buyout Process
- Research: Based on the VIN, year, make, model of your vehicle, and state law, we determine its value and make you an offer based on your ability to repay and our credit criteria.
- Offer: We provide the loan offer we can finance if you’re pre-approved.
- Coordinate: When determining our offer, we take into account any outstanding balance with the leasing company.
- Payoff: We pay off the remaining balance owed to the leasing company directly, and you keep driving the car while you repay the new title loan.
Once the lease balance is paid off and the title lands in your name, the same vehicle that couldn’t secure a loan yesterday can secure one today.
What Does a Lease Buyout Actually Cost?
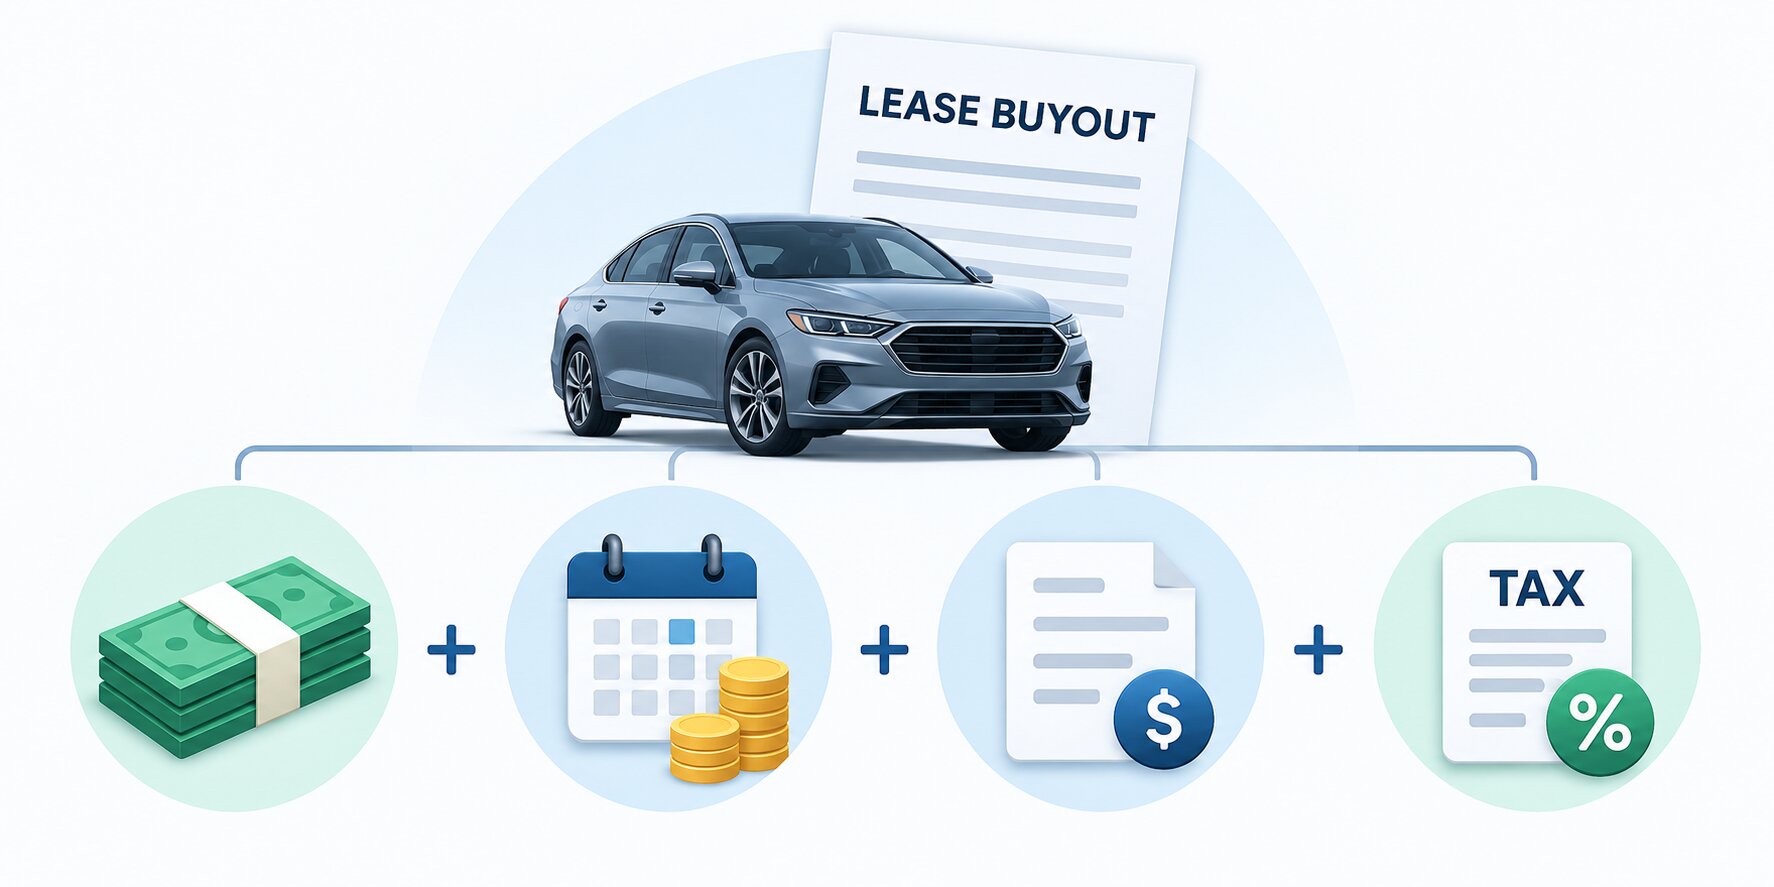
A lease buyout price is made up of four components, and it’s worth comparing that total to what a title loan could realistically offer before you commit.
- Residual value of the car
- Remaining lease payments
- Contractual fees
- Applicable sales tax
You can estimate the car’s buyout price by looking up the residual value in your lease contract and adding any remaining payments.
For example, if your car’s residual value is $15,000 and you owe six more payments of $500, your buyout price would be about $18,000.
That buyout price is only half the picture. We set your title loan amount by reviewing the vehicle’s market value alongside your ability to repay, not a fixed percentage of the car’s value, so the amount we could offer may or may not cover an $18,000 buyout.
Title loan amounts are commonly around 25%–50% of the vehicle’s value, depending on the borrower’s ability to repay, the car’s equity, and applicable state laws and regulations.
If it doesn’t, you’d need to cover the difference yourself, which is exactly the kind of number worth confirming with us before you start the paperwork.
Buyout terms, including whether fees are negotiable or an early buyout is allowed, vary by lease contract, so reading your lease is a necessary first step.
Before You Commit
- A buyout price can typically be paid with a check or financed.
- Research your car’s current market value before deciding – see our FAQ below on what happens if it’s worth less than the buyout price.
- The residual value usually isn’t negotiable, but fees sometimes are.
- Leases can typically be bought out before or after their expiration date.
Talk It Through First
Not sure how the numbers work out for your specific lease?
Call 1-888-700-8900 to talk it through before you apply.
Is This the Same as a Title Loan on a Financed Car?
No. A leased car and a financed car are different situations, even though both involve still owing money on the vehicle.
If your car is financed rather than leased, you already hold the title, just with a lien on it. That’s a more direct path to a title loan, and it’s covered on our dedicated title loan on a financed car page.
The buyout pathway on this page is specifically for leased vehicles, since the two situations shouldn’t be treated interchangeably.
What Should You Do Before Applying?
Because a lease buyout involves more moving parts than a standard title loan, it’s worth calling before you start the application.
The exact buyout price, our loan-to-value terms, and whether the numbers work for your specific lease need to be confirmed on a case-by-case basis. Have your lease contract handy when you call.
The residual value and remaining payment count are the two numbers that determine whether a buyout title loan makes sense for you.
This is a genuine know-before-you-go recommendation, not a sales tactic. The math above is specific enough that a quick call can save you a wasted application.
Title Loan on a Leased Car FAQs
Can You Get a Title Loan on a Leased Car?
No, not directly. The leasing company holds the title during the lease term, and a title loan requires a clean title in your name. The one exception is a lease buyout, which transfers the title to you first.
What is a Lease Buyout, and How Does it Work with a Title Loan?
A lease buyout doesn’t have to wait until your lease ends; you can typically pay it off early at any point during the term.
Once the lease balance is paid and the title transfers to you, we evaluate the vehicle the same way we would any other car you own outright, based on its value and your ability to repay.
How Much Does a Lease Buyout Typically Cost?
It depends on your specific lease, since the residual value, remaining payments, and fees vary contract to contract.
The most accurate way to find your real number is to request a payoff quote from your leasing company rather than relying on a general estimate.
Is a Title Loan on a Leased Car the Same as a Title Loan on a Financed Car?
No, and the easiest way to tell which one applies to you is to check your paperwork.
A lease agreement lists a leasing company as the title holder. A financed car’s title lists you as the owner, with a lienholder noted separately. If it’s the latter, our title loan on a financed car page covers your situation.
Why Should I Call Before Applying for a Lease Buyout Title Loan?
A lease buyout has more moving parts than a standard title loan, and the numbers are specific to your lease.
Calling first lets us confirm the buyout price and what we could realistically offer, so you’re not applying without knowing whether the math works.
What Happens if the Buyout Price is More Than the Title Loan I Could Get?
You’d need to cover the difference yourself, whether through savings or another funding source. This is exactly why it’s worth calling to run the numbers before committing to a buyout.
What if My Car is Worth Less than the Lease Buyout Price?
If your car’s current market value is lower than the buyout price, buying out the lease may not make financial sense.
Essentially, you’d be paying more to own the car than it’s actually worth. It would also limit what a title loan could offer, since we base the loan amount on the vehicle’s market value, not the buyout price.
The Bottom Line
A leased car can’t secure a standard title loan directly, but a lease buyout might get you there. Buying out your lease transfers the title into your name, and once that happens, the same vehicle that couldn’t qualify yesterday can qualify today.
Call us to run the numbers on your specific lease before you apply, or apply online to see what you may qualify for.