

Home How do Title Loans Work – The Complete Guide
How Do Title Loans Work? What to Expect With Us

Fact-Checked
Close
Each article is reviewed by our editorial team and fact-checked for accuracy using credible sources. We regularly update content to reflect current information (see last update at top of article). Learn more about our editorial standards.
How much could I qualify for?
Get a free quote. It’s fast, secure, and simple.
Over 375,000+ People Helped Since 2007
Trusted & Accredited:

A title loan lets you borrow money against a vehicle you own, using its title as collateral. You keep driving the car while you repay, and once the loan is paid in full, you get your title back.
Here’s how that works with us, from applying to getting your title back, and what it costs in the states where most of our customers live. Title loans are expensive, and your car is at risk if you don’t repay, so it’s worth understanding each step before you borrow.³ ⁴
Key Takeaways
- A title loan uses an eligible vehicle, such as a car, truck, SUV or motorcycle, as collateral.
- You keep driving your car while you make payments.
- We look at your verifiable income alongside your car’s value to decide how much you can borrow.
- Interest and fees mean you pay back more than you borrow, so check the total cost in your offer.
- Your car secures the loan. If you don’t repay, you could lose your car.⁵
Table of Contents
- What Is a Car Title Loan?
- How Do Title Loans Work Step by Step?
- What Do You Need to Qualify for a Title Loan?
- How Much Can You Borrow?
- What Does a Title Loan Cost?
- How Does Title Loan Repayment Work?
- What Happens If You Miss a Title Loan Payment?
- Are Title Loans Available in Every State?
- Is a Title Loan Right for You?
- How Do Title Loans Work? FAQs
What Is a Car Title Loan?
A car title loan lets you borrow money using the value of a vehicle you already own. The loan is secured by your vehicle, but you keep the car and can continue driving it while you make your payments.
That’s different from a pawn loan, where you usually have to leave the item, such as jewelry or another valuable, with the lender until the loan is repaid.
Montana Capital Car Title Loans® offers title loans on cars, trucks, SUVs, motorcycles, RVs, and some off-road vehicles.
How Do Title Loans Work Step by Step?
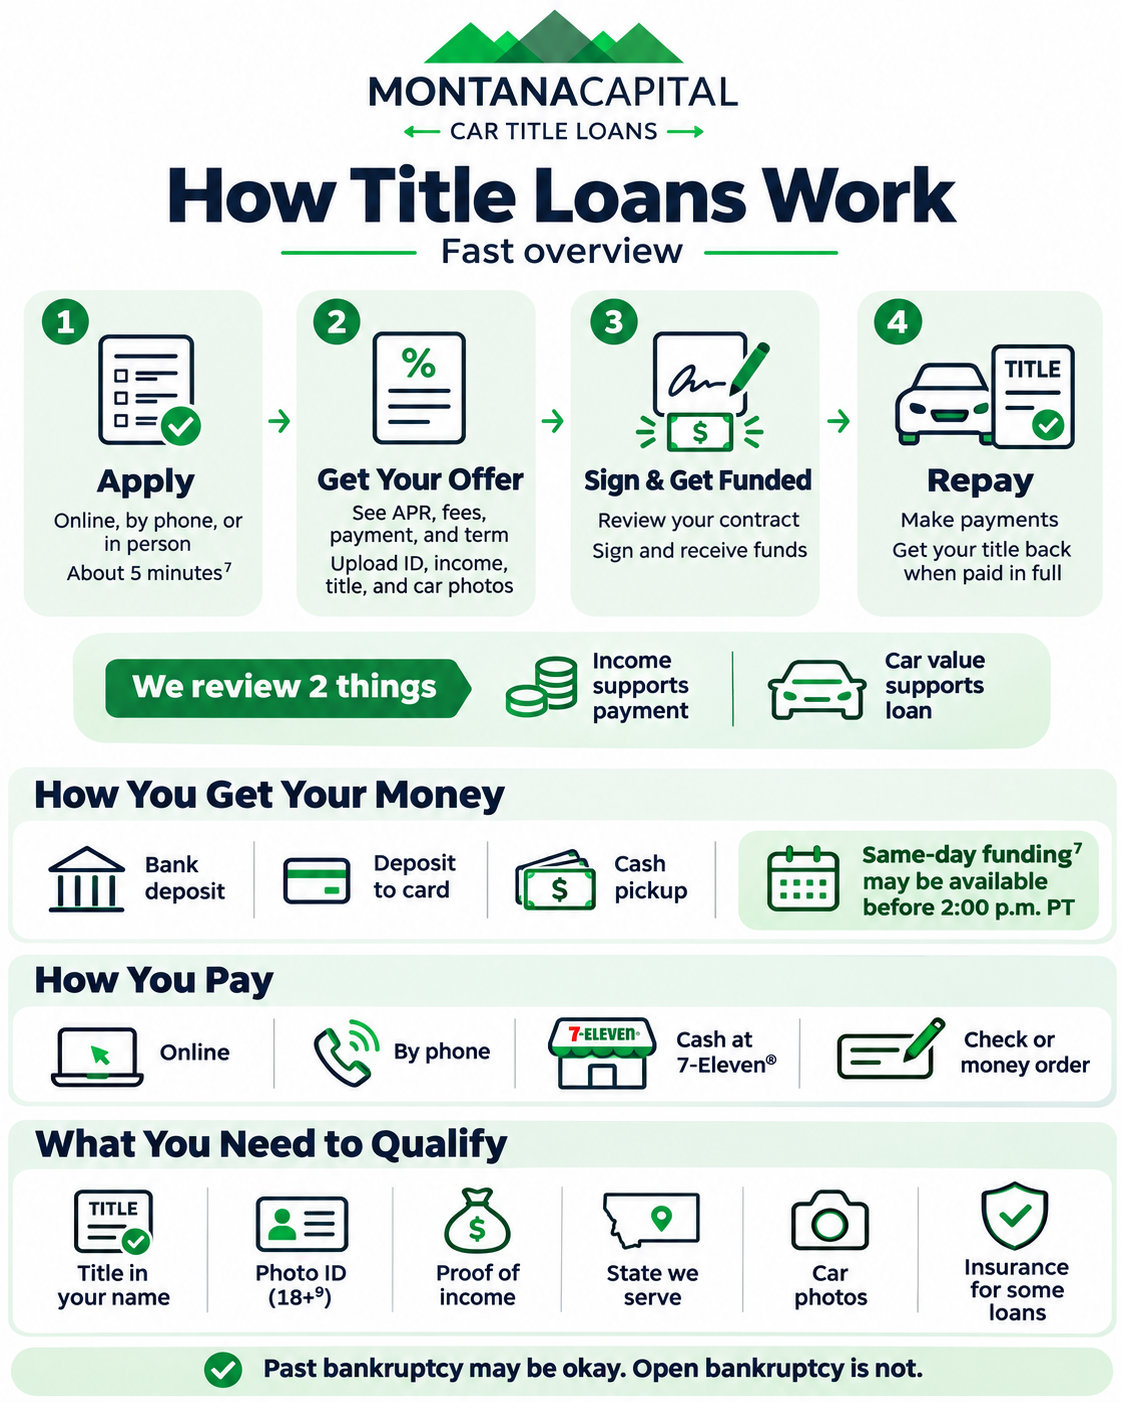
- Apply. Apply online or by phone in about 5 minutes⁷ with your personal details, income information, and car details to see if you’re pre-approved. You can also apply at one of our locations.
- Get your offer. Once you qualify, you get a free offer showing the APR, fees, payment, and term, all set according to your state’s law. Then you upload your ID, proof of income, title, and vehicle photos.
- Sign and get funded. Review your contract, ask any questions you need clarified, and make sure you can make the payments as agreed. Then you sign and get funded.
- Repay and get your title back. Keep driving your car while you make your payments as agreed. Once the loan is paid in full, your title is returned to you.
In many cases, you can finish everything online or by phone, including the vehicle inspection, using photos from your phone. Some applicants may still need to visit one of our locations because of state law or their individual circumstances. Read more about applying online.
Under our policy, some loans may require a GPS tracking device to be installed on the vehicle at no extra charge. If a GPS device is required, we will let you know before you sign the loan agreement.⁸
How You Get Your Money and Make Payments
Same-day funding⁷ may be possible when your application is approved before 2:00 p.m. PT on a business day. You can choose direct deposit to a bank account, a deposit to a card, or cash pickup at a MoneyGram location with no bank account needed.
You can pay online, by phone, in cash at 7-Eleven through PayNearMe, or by check or money order by mail. Our how to pay page has the details.
What Do You Need to Qualify for a Title Loan?
These are our title loan requirements:
- A lien-free title in your name, or one that is nearly paid off
- A government-issued photo ID, and you must be 18 or older⁹
- Proof of income
- Residence in a state we serve
- Interior and exterior photos of your car for inspection
- Proof of insurance for loans over $5,000, and in some cases for lower amounts depending on the car’s condition
A past bankruptcy doesn’t disqualify you. An open bankruptcy does.
Why We Ask for Proof of Income
Your income shows us you can afford the payment, and it doesn’t have to come from a job. Other income, such as disability, retirement, or unemployment pay, can count.
We check this because a loan you can’t afford can lead to extra costs, default, and possibly losing your car. We’d rather approve an amount that fits your budget than the most your car could support.
Do You Need Good Credit?
We do not run a credit check for pre-approval. If you decide to move forward with a loan, we may review credit reports from TransUnion, Equifax, LexisNexis, or FactorTrust as part of final approval. Credit is not the main approval factor; we focus primarily on your verifiable income and vehicle equity. Applicants with bad credit are welcome to apply.
Checking your pre-approval does not affect your credit score.
How Much Can You Borrow?
Our loans range from $500 to $50,000, and you can borrow up to 70% of your car’s value. The final amount depends on your car, your verifiable income, and your state’s law.⁴
For example, in California, if your car is worth $8,000, the most we could consider is $5,600. Your offer could be lower if a smaller payment fits your income better, which is why two people with the same car can get different offers.
State law can change these numbers. In California, our loans start at $2,600. Tennessee and Virginia cap title loans at $2,500. In Texas cities such as Houston, Dallas and San Antonio, local rules limit the loan to the lower of 70% of the car’s value or 3% of your yearly income.
What Does a Title Loan Cost?
Your APR depends on your state, the loan amount, and your ability to repay. It can be up to 175% APR, but many states cap it much lower.
In California, where many of our customers live, loans of $2,500 to $9,999 are capped at 36% a year plus the Federal Funds Rate, about 39.88% as of November 2026. Here’s what that means at the maximum rate:
| Loan | 12 months | 24 months |
| $2,600 | $266/mo, $595 interest | $159/mo, $1,214 interest |
| $4,000 | $410/mo, $916 interest | $244/mo, $1,868 interest |
| $6,000 | $614/mo, $1,374 interest | $367/mo, $2,802 interest |
*Based on a 39.88% annual interest rate in California. Does not include the $75 administrative fee.
Your offer shows your exact APR, fees, and total cost before you sign. There’s no prepayment penalty, so paying early or paying more than the minimum lowers your finance charges.⁶ Our title loan calculator shows other amounts and terms.
How Does Title Loan Repayment Work?
Most of our loans have monthly payments over a set term of up to 36 months, shorter where state law requires. Each payment covers interest and part of the balance.
A few states work differently. In Georgia and Tennessee, terms are 30 days and can be renewed, and each renewal adds interest. Delaware loans run up to 180 days, and Virginia loans up to 24 months.
Once your final payment clears, we send your title back. In some circumstances, we may return a lien-release form instead of the signed-off title.
What Happens If You Miss a Title Loan Payment?
We recommend calling us at (818) 503-9393 before you miss a payment. Where allowed by state law, we may review options such as changing the due date or setting up a payment plan. Repossession is a last resort and is handled in accordance with state law.
Your car secures the loan. If you don’t repay, you could lose your car.⁵ Our guide on title loan repossession explains what happens and what it can cost.
Are Title Loans Available in Every State?
Title loans aren’t available everywhere, and each state sets its own limits on amounts, terms, and rates. We currently lend in California, Delaware, Florida, Georgia, Indiana, Kentucky, Louisiana, Ohio, Oklahoma, Tennessee, Texas, and Virginia. Find our locations for details on your state.
Is a Title Loan Right for You?
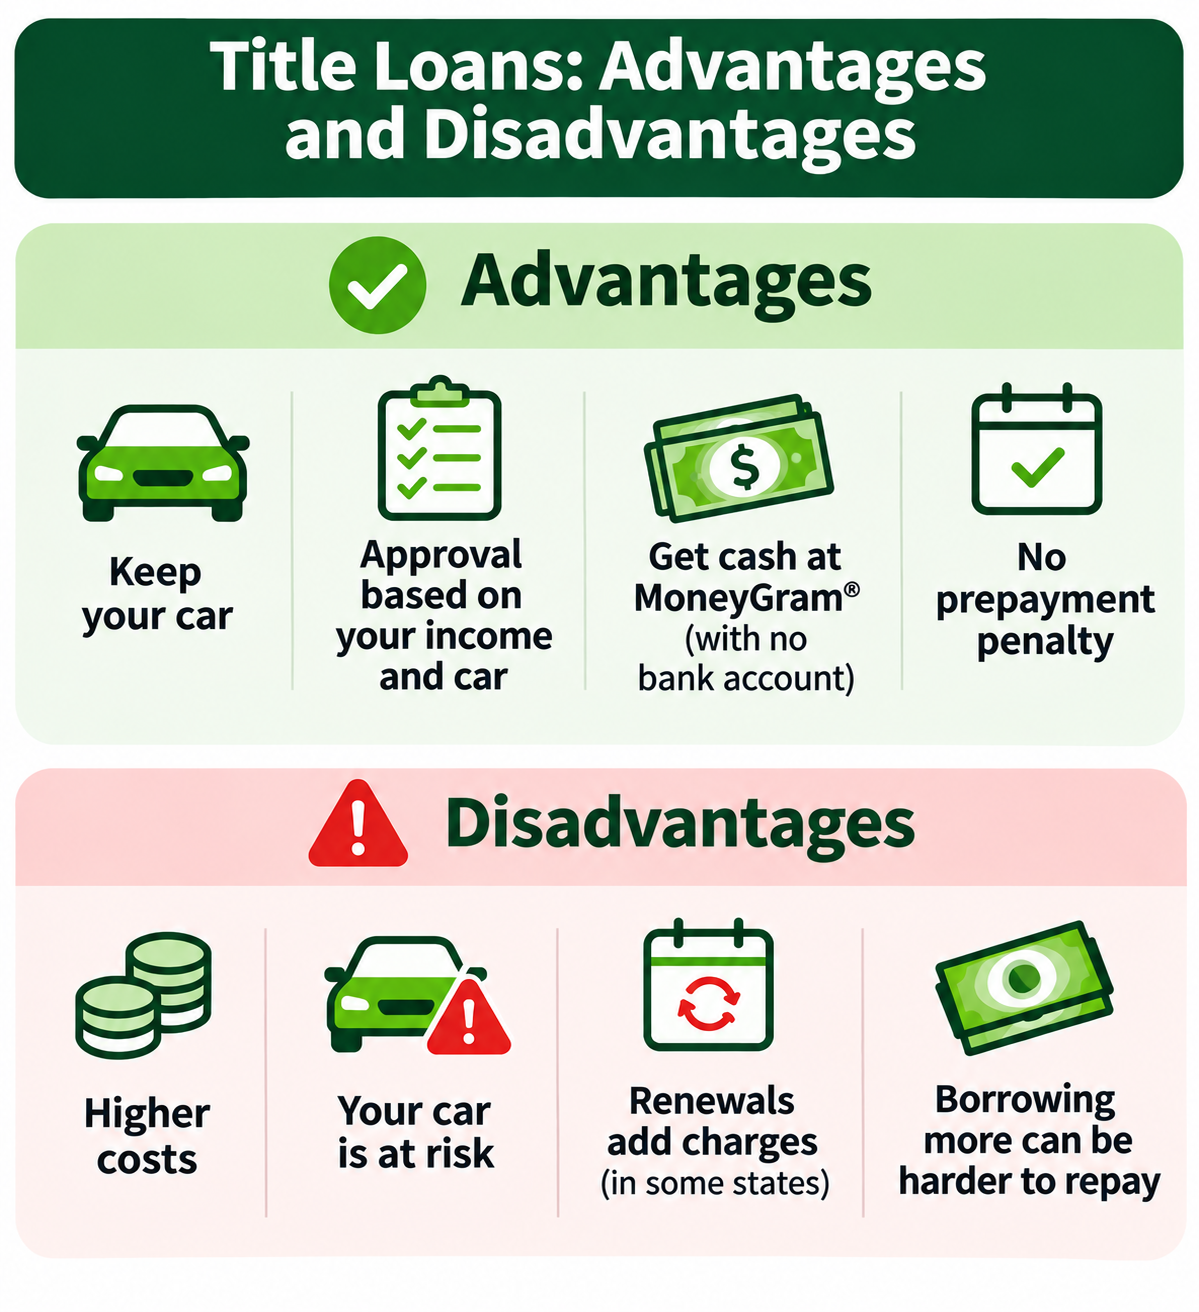
Title loans are best kept for real emergencies when lower-cost credit isn’t available, not for everyday spending.⁶ One may make sense if you can afford the payments in your offer, you understand the total cost, and lower-cost options won’t work for you. Borrowing only what you need also makes the loan easier to repay.
Before you borrow, compare options like a credit union loan, a payment plan with the bill’s creditor, or a nonprofit credit counselor. The FTC’s guide, What To Know About Payday and Car Title Loans, is a good place to compare.
How Do Title Loans Work? FAQs
How Do Auto Title Loans Work for Cars, Trucks and Motorcycles?
They all work the same way. We value each vehicle on its make, model, year, mileage, and condition; you keep driving it while you repay, and we return the title once the loan is paid in full.
Can I Get a Title Loan if My Car Isn’t Paid Off?
You may still qualify if your car is nearly paid off. Read how title loans on financed cars work.
Can I Sell My Car While I Have a Title Loan?
Not while we hold the title, because the loan has to be paid off first. If you need to sell, call us at (818) 503-9393 for your payoff amount. Once the loan is paid in full, we release the title so you can complete the sale.
What if There Are Two Names on the Title?
It depends on how the names are listed. If the title says “or” between the names, one owner can usually apply alone. If it says “and,” both owners usually need to be part of the loan.
Can I Refinance a Title Loan I Have With Another Lender?
Yes, we may be able to refinance a title loan you already have with another lender. Read how title loan refinancing works.
Ready to see what you may qualify for? Check your eligibility online or call 1-888-700-8900.
Questions or complaints? Call (818) 503-9393. You can also contact your state regulator.
Editorial Disclosure: Montana Capital Car Title Loans® (NMLS ID 2249848) is a licensed direct lender. This content is informational only and does not offer legal or financial advice. Terms, APRs, and availability may vary by state and borrower qualifications.