



Sometimes, yes. A car with a salvage or rebuilt title can qualify for a title loan, but approval isn’t automatic.
We look at what your car is worth today, its condition and title status, and whether your income can comfortably cover the payments. State law also sets how much you can borrow and for how long, so the answer can depend on where you live.³ ⁴
Below, we explain how a salvage or rebuilt title changes our review, what we ask for, and what to do if your car doesn’t qualify.
Key Takeaways
- A salvage title doesn’t rule your car out on its own, but we decide case by case.
- A rebuilt title shows the car was repaired and passed a state inspection. That gives us more to go on, but it still isn’t a guarantee.
- Have your title, ID, proof of income, and clear photos of the car ready, including any repaired areas.
- Your car secures the loan. If you don’t repay, you could lose your car.⁵
What Is a Salvage Title?
A salvage title means an insurance company declared the car a total loss, usually after a serious crash, flood, hail, or theft. The exact rule depends on your state.
Many states won’t let you register or drive a salvage car until it’s repaired and passes a state inspection. Once it does, it gets a rebuilt title.
How We Decide on a Salvage Title Car Loan
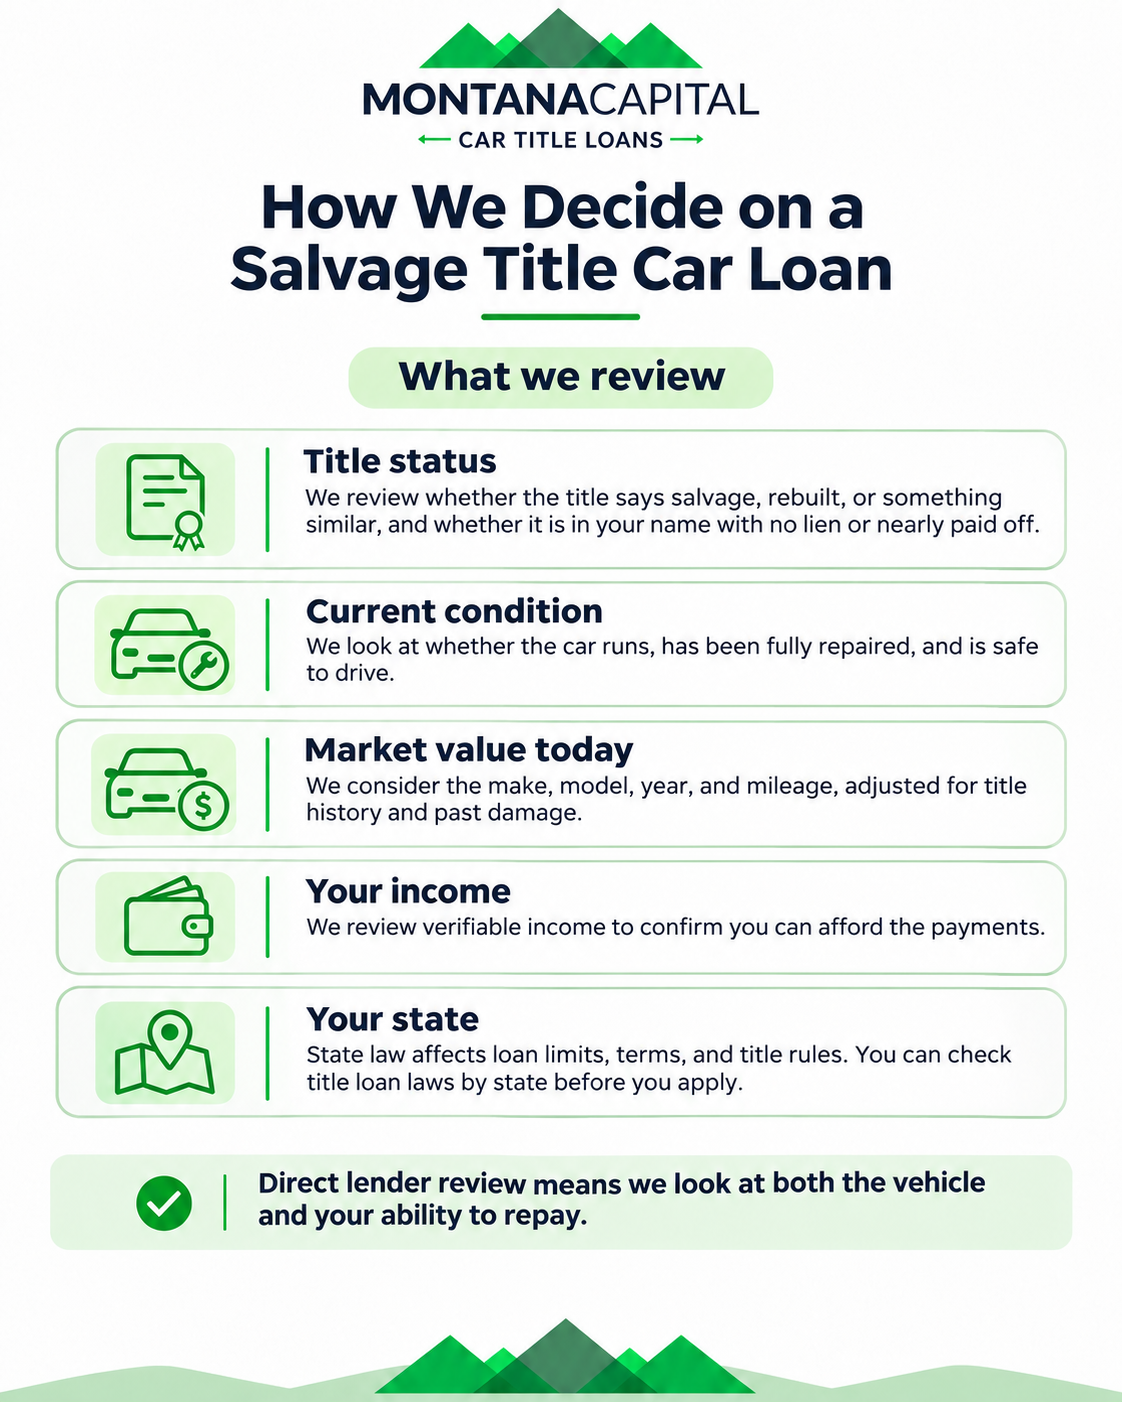
We take a closer look at the car than we would with a clean title. These are the main things we review:
- Title status. Whether it says salvage, rebuilt, or something similar, and whether it’s in your name with no lien, or nearly paid off.
- Condition and repairs. Whether the car runs, is safe to drive, and how well past damage was fixed.
- Value today. Make, model, year, and mileage, adjusted for the title history.
- Your income. Proof that you can afford the payments.
- Your state. State law sets loan limits and terms. For example, Tennessee and Virginia cap title loans at $2,500. You can check title loan laws by state before you apply.
Salvage title financing works best when the car still has solid value, and your budget has room for the payment. If one of those is missing, we may offer less than you asked for or decline the application.
Many people expect a title loan to be all about the car, but your ability to repay matters just as much. A payment you can’t keep up with can lead to extra costs, default, and possibly losing your car.
That’s why we ask for proof of income and aim for a payment that fits your budget, not the biggest loan we can make.
Can You Get a Loan on a Rebuilt Title?
Yes, a rebuilt title can qualify, and it usually has a better chance than a salvage title because the car has been repaired and passed a state inspection.
| Salvage Title | Rebuilt Title | |
| What it means | An insurer declared the car a total loss | The car was repaired after a salvage title and passed a state inspection |
| Can you drive it? | Often not legal on the road until it’s repaired and inspected | Usually can be registered and driven |
| How we look at it | Harder to use as collateral, especially if not yet repaired | Reviewed on value and condition, adjusted for its history |
The rebuilt label stays on the title for good, though, so the car is usually worth less than the same model with a clean title. Some states use other names, such as “reconstructed” or “prior salvage.”
If your car still has a salvage title, finishing the repairs and getting it inspected before you apply may be worth it. Our guide on turning a rebuilt title into a clean title explains what comes next.
What Borrowers Often Get Wrong
- “A newer car means a bigger loan.” Not always. A newer car with a salvage title can be worth less than an older car with a clean title.
- “Repairs erase the history.” The car may run perfectly, but the salvage or rebuilt label stays on the title and still affects its value.
- “Bad credit means I won’t qualify.” Credit is not the main approval factor. We focus on your income and the car’s value.³
- “The lender wants to approve as much as possible.” We’d rather approve an amount you can repay comfortably.
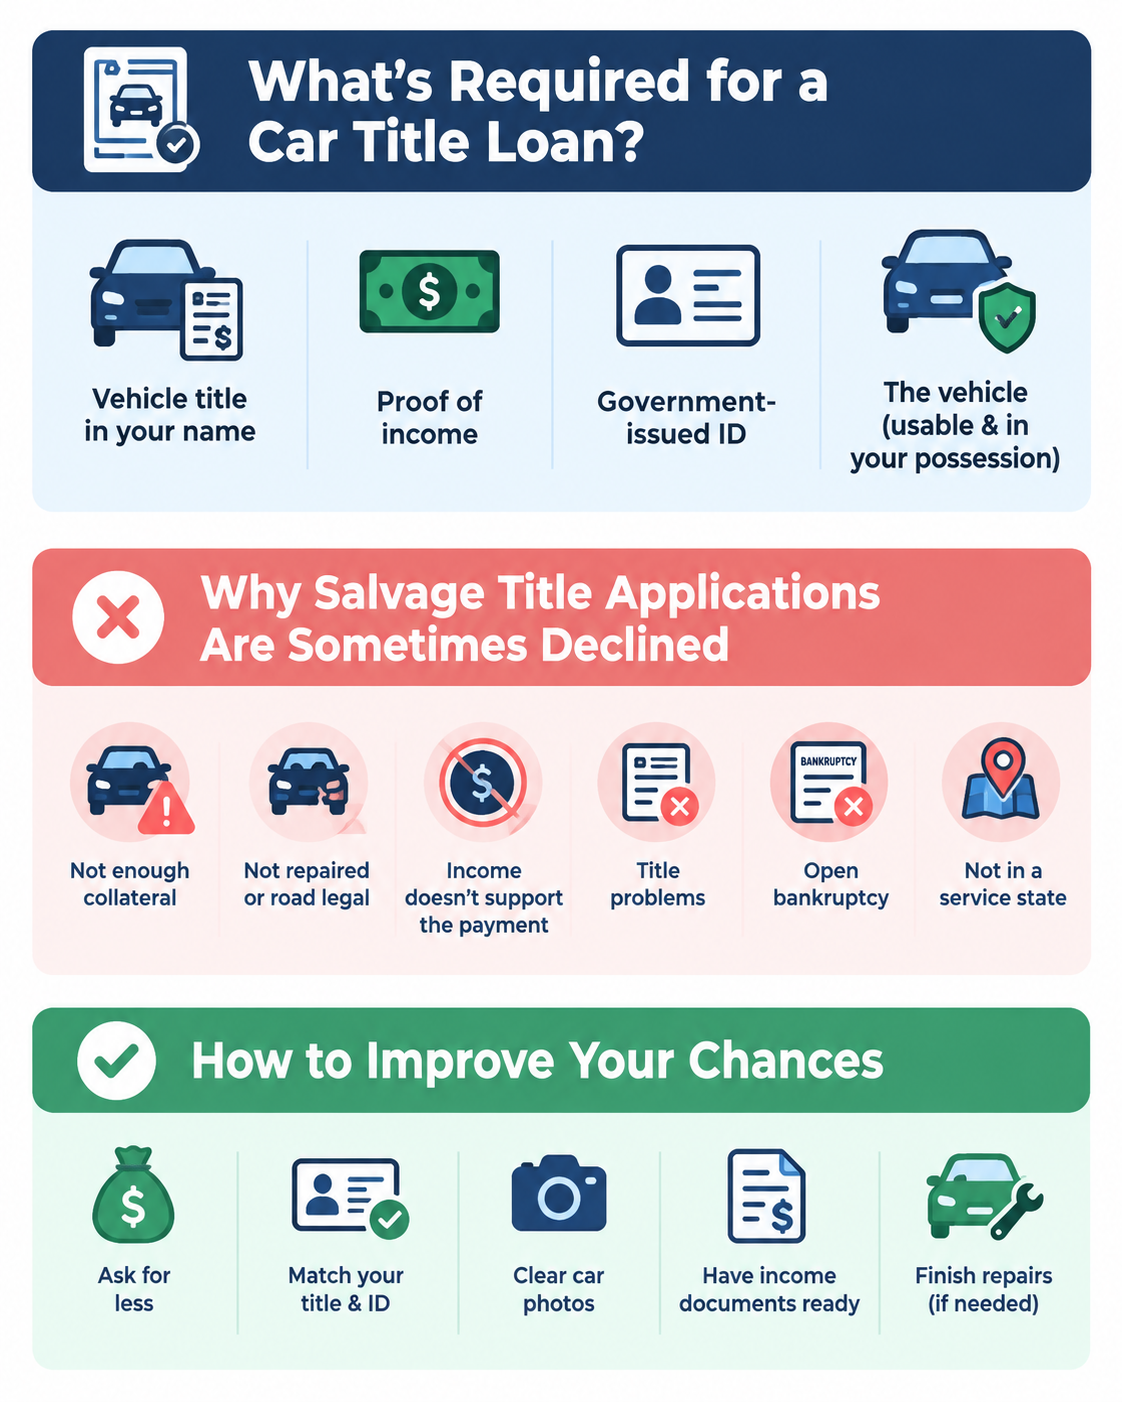
Why Salvage Title Applications Are Sometimes Declined
When we can’t approve a salvage title loan, it’s usually for one of these reasons:
- Not enough collateral. After the title history and past damage are factored in, the car may not provide enough collateral to support the requested amount.
- The car isn’t repaired or road legal. A car that can’t be registered or driven safely is hard to use as collateral.
- Income doesn’t support the payment. We can’t confirm enough steady income to cover the loan comfortably.
- Title problems. The title isn’t in your name, another lender holds a lien, or the name doesn’t match your ID.
- An open bankruptcy. A past bankruptcy doesn’t disqualify you, but an open one does.
- Location. You live in a state we don’t currently serve.
Improve Your Chances of Approval
- Ask only for what you need. A smaller amount is easier to fit within your car’s value and your budget.
- Make sure the name on your title matches your ID.
- Take clear, well-lit photos of the whole car, including repaired areas and the mileage on the dashboard.
- Have your income documents ready before you start.
- If your car still has a salvage title, think about finishing repairs and getting the rebuilt title first.
What Do You Need to Apply for a Salvage Title Loan?
You’ll need the same basics as any of our title loans: your title, a photo ID, proof of income, and photos of your car. With a salvage or rebuilt title, two extras can speed up our review:
- Clear photos of any repaired areas and the mileage on the dashboard.
- Your state inspection paperwork and repair receipts, if the car has a rebuilt title.
In many cases, the vehicle inspection can be done online with photos. With a salvage or rebuilt title, we may need a closer look, and some applicants may need to visit a location because of state law or their individual circumstances.
What Are the Risks of a Salvage Title Loan?
- Title loans are expensive. Your APR depends on your state, the loan amount and your ability to repay. Our title loan calculator shows how payments change with different amounts.
- Your car secures the loan. If you don’t repay, you could lose your car.⁵ With a salvage-title car, that can be harder to recover from, because the car may be worth less and be harder to replace.
We recommend calling us at (818) 503-9393 before you miss a payment. Where allowed by state law, we may review options such as changing the due date or setting up a payment plan. Repossession is a last resort and is handled in accordance with state law.
Title loans are meant for real emergencies when lower-cost credit isn’t available.⁶ There’s no prepayment penalty, so paying early can lower your total cost. Before you borrow, compare options like a credit union loan, a payment plan with the bill’s creditor, or a nonprofit credit counselor.
Frequently Asked Questions
Can You Get a Title Loan on a Salvage Title?
Some salvage-title cars can qualify, but it’s case by case. We look at the car’s current value and condition, its title status and your ability to repay.³
Can You Get a Loan on a Rebuilt Title?
A rebuilt title can qualify when the car’s value and your income support the loan amount. A rebuilt title usually lowers the value, so your offer may be smaller than for the same car with a clean title.
Is a Rebuilt Title Better Than a Salvage Title for a Title Loan?
A rebuilt title shows the car was repaired and passed a state inspection, which gives us more to work with. It doesn’t guarantee approval, and we still review the whole application.
How Much Can You Borrow on a Salvage or Rebuilt Title?
We can lend up to 70% of your car’s value, based on the car, your verifiable income, and state law. With a salvage or rebuilt title, that value starts lower.
Will I Need a Vehicle Inspection for a Salvage Title Loan?
Yes, we inspect every car. In many cases, you can do it online with interior and exterior photos. With a salvage or rebuilt title, we may ask for extra photos, and some applicants may need to visit a location depending on state law or their circumstances.
Can I Get a Salvage Title Loan With Bad Credit?
We do not run a credit check for pre-approval. If you decide to move forward with a loan, we may review credit reports from TransUnion, Equifax, LexisNexis, or FactorTrust as part of final approval. Credit is not the main approval factor; we focus primarily on your verifiable income and vehicle equity. Applicants with bad credit are welcome to apply.
Checking your pre-approval does not affect your credit score.
Ready to see whether your car may qualify? Check your eligibility online or call 1-888-700-8900.
Questions or complaints? Call (818) 503-9393. You can also contact your state regulator.