



Title loan APRs often reach about 300%, according to the FTC and Pew Charitable Trusts. But each state sets its own limit, so what you pay depends mostly on where you live.
In California, a $5,000 title loan over 24 months at the highest rate the state allows costs about $306 a month and $2,335 in interest. In Florida, a $2,000 title loan costs about $49 in interest for every 30 days you owe the full amount.
At a Glance
✓ California caps interest at 36% a year plus the Federal Funds Rate on loans from $2,500 to under $10,000.
✓ Florida caps interest at 30% a year on the first $2,000, with lower rates on larger balances.
✓ Texas doesn’t cap the fee for arranging your loan, and that fee makes up most of the cost, so check the APR and total cost on your disclosure.
✓ Your offer shows your exact APR, payment, and total cost before you sign.
Editorial Disclosure: Montana Capital Car Title Loans® (NMLS ID 2249848) is a licensed direct lender. This content is informational only and does not offer legal or financial advice. Terms, APRs, and availability may vary by state and borrower qualifications.
What a Title Loan Costs in California
California law caps interest on loans from $2,500 to under $10,000 at 36% a year plus the Federal Funds Rate. The Federal Funds Rate used is the one in effect on the first day of the month before your loan is signed.
For loans signed in November 2026, that rate is 3.88%, so the cap is 39.88%. Our California title loans start at $2,500.
Here’s what you’d pay at that maximum rate (accurate as of November 2026).
12-Month Loan
| Loan Amount | Monthly Payment | Total Interest |
|---|---|---|
| $2,500 | $256 | $572 |
| $3,000 | $307 | $687 |
| $4,000 | $410 | $916 |
| $5,000 | $512 | $1,145 |
| $6,000 | $614 | $1,374 |
| $8,000 | $819 | $1,831 |
24-Month Loan
| Loan Amount | Monthly Payment | Total Interest |
|---|---|---|
| $2,500 | $153 | $1,167 |
| $3,000 | $183 | $1,401 |
| $4,000 | $244 | $1,868 |
| $5,000 | $306 | $2,335 |
| $6,000 | $367 | $2,802 |
| $8,000 | $489 | $3,736 |
Estimates at California’s maximum rate of 39.88% for loans signed in November 2026, rounded to the nearest dollar.
On loans under $5,000, an administrative fee of up to $75 may be added. On loans of $5,000 or more, any fee counts toward the rate cap. Your offer may come in lower.
In Los Angeles, our average funded title loan in 2025 was $5,066. That puts the $5,000 row close to what many of our California borrowers take out.
California loans in this range must run at least 12 months. Loans of $10,000 or more have no state rate cap, so they carry higher APRs, and your offer shows the exact figure.
What a Title Loan Costs in Florida
Florida law caps title loan interest at 30% a year on the first $2,000, 24% on the part from $2,000 to $3,000, and 18% on anything above $3,000. We lend up to $10,000 with our Florida title loans.
Here’s the interest for every 30 days on the full amount at those maximum rates.
| Loan Amount | Interest for 30 Days | Yearly Rate Overall |
|---|---|---|
| $1,000 | $25 | 30% |
| $2,000 | $49 | 30% |
| $3,000 | $69 | 28% |
| $4,000 | $84 | 25.5% |
| $5,000 | $99 | 24% |
| $10,000 | $173 | 21% |
Estimates at Florida’s maximum rates, rounded to the nearest dollar. Your disclosure shows the exact finance charge and APR before you sign.
In Miami, our average funded title loan in 2025 was $4,064. A loan of that size costs about $85 in interest for every 30 days at the cap.
Paying Down the Balance Lowers Your Cost in Florida
Interest is charged on what you still owe. If you only pay the interest, a $2,000 loan costs about $296 over six months, and you still owe the full $2,000.
Paying $500 toward the balance every 30 days instead clears the loan in four months for about $123 in interest.
What a Title Loan Costs in Texas
For Texas title loans, we arrange your loan as a Credit Access Business. A third-party lender charges interest, capped at 10% a year, and we charge a separate fee for arranging the loan.
Texas law doesn’t cap that fee, so it makes up most of what a Texas title loan costs. Your disclosure shows the exact fee, interest rate, and total cost in writing before you sign.
In Houston, our average funded title loan in 2025 was $2,237.
How Texas Loans Are Repaid
Texas loans can run up to 180 days, including any renewals. Many cities, including Austin, Dallas, Houston, and San Antonio, add their own limits.
In those cities, a loan can’t be more than 3% of your gross yearly income or 70% of your car’s retail value, whichever is less. It can have no more than four installments, and each one must pay off at least 25% of the amount borrowed.
When you compare Texas offers, look at the total cost for the whole loan, not just the first payment.
Title Loan Interest Rates in Other States We Serve
| State | Rate Rule | Term |
|---|---|---|
| Virginia | 36% a year, plus a monthly fee of the lesser of $15 or 8% of the loan. Loans up to $2,500. | Up to 24 months |
| Tennessee | 2% a month, plus a fee of up to 20% of the original amount every 30 days. Loans up to $2,500. | 30 days, renewable |
| Georgia | Up to 25% of the amount borrowed every 30 days for the first 90 days, then 12.5%. | 30 days, renewable |
| Louisiana | 36% a year on the first $1,400, with lower rates on larger balances, down to 21% above $7,000. | At least 60 days |
| Oklahoma | 32% a year plus the Federal Funds Rate on the first $7,000, with lower rates on larger balances. | Equal monthly installments |
| Delaware | No state rate cap. | Up to 180 days, including renewals |
In Georgia, car title loans are called title pawns under the state’s Pawnbroker Act. In Georgia and Tennessee, each 30-day renewal adds another round of charges, so the cost grows fast if you only pay the charges.
Indiana, Kentucky, and Ohio have their own rules too. You can compare car title loan rates in every state on our title loan laws by state page.
What Decides Your Title Loan APR
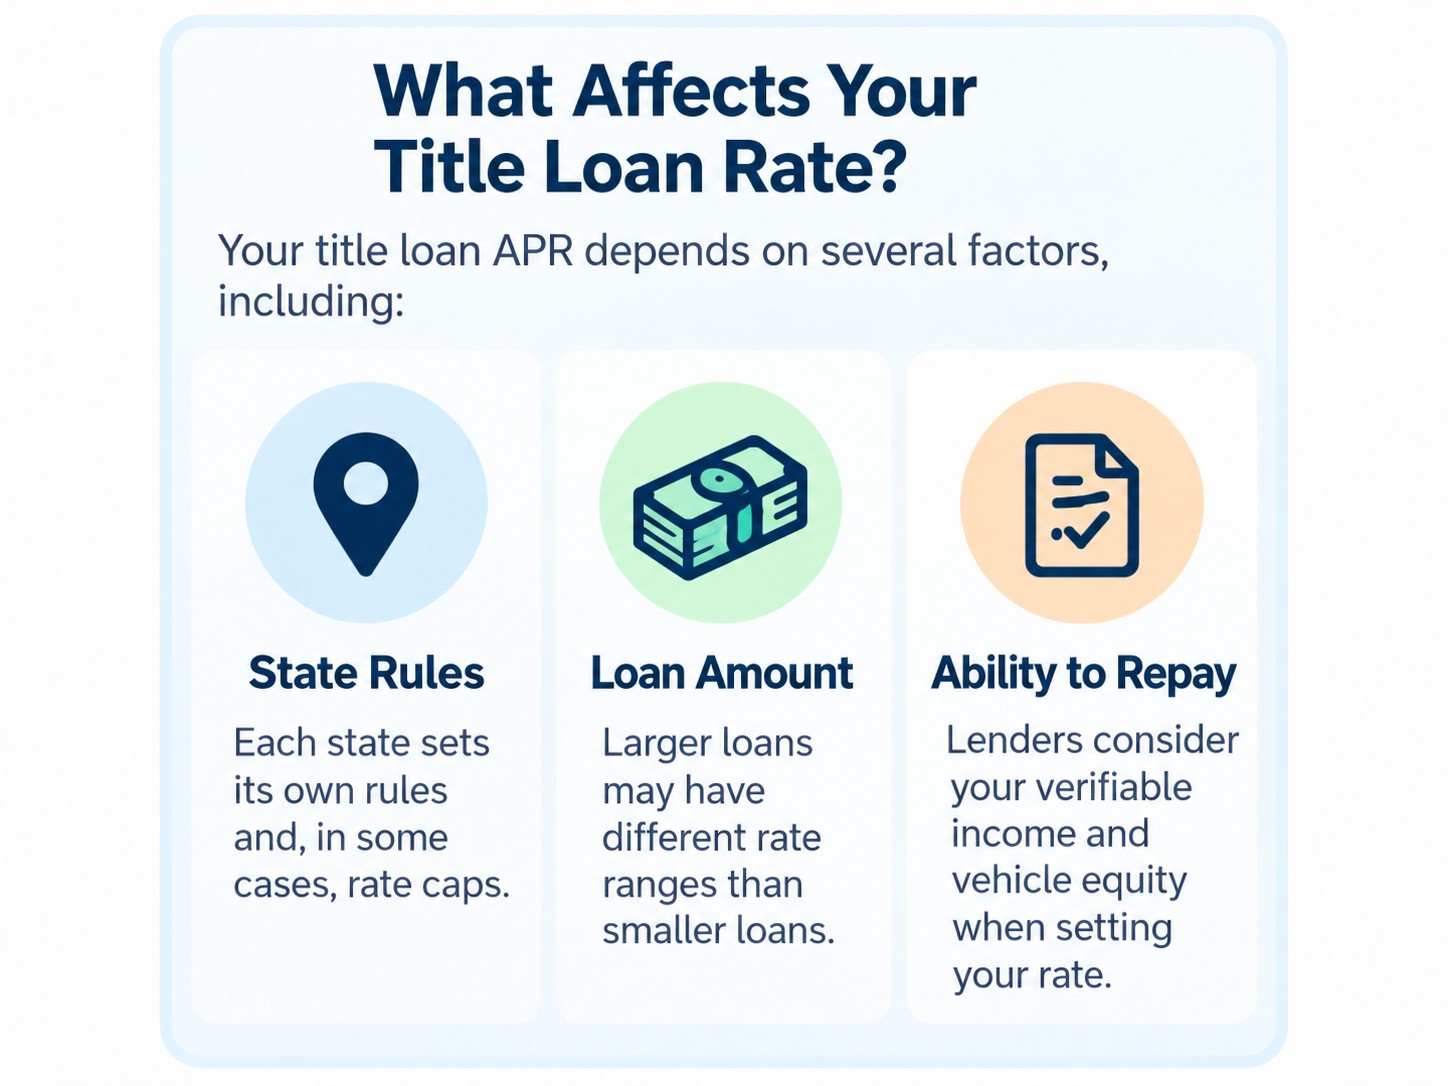
Your state sets the highest rate we can charge, and our APR is typically up to 175%, lower where state law caps it.
Within those limits, we review your vehicle’s market value alongside your ability to repay so the loan amount is appropriate for your financial situation.
How to Pay Less on a Title Loan
Three choices make the biggest difference to the interest on title loans.
Borrow only what you need. On a 24-month California loan at the cap, each $1,000 you don’t borrow saves about $467 in interest.
Choose the shortest term you can afford. On a $5,000 California loan, picking 12 months instead of 24 raises the payment by about $206 but saves about $1,190 in interest.
Pay early when you can. We don’t charge a prepayment penalty, so extra payments lower the interest you pay.
You can test different amounts and terms with our title loan calculator.
What Happens If You Can’t Make a Payment
Your car secures the loan. If you don’t repay, you could lose your car.
We recommend calling us at (818) 503-9393 before you miss a payment. Where allowed by state law, we may review options such as changing the due date or setting up a payment plan. Repossession is a last resort and is handled in accordance with state law.
Before you borrow, compare options like a credit union loan, a payment plan with the bill’s creditor, or a nonprofit credit counselor.
You can also contact your state regulator.
FAQ
How Much Are Title Loan Payments?
It depends on your state, loan amount, and term. In California, at the legal cap, each $1,000 you borrow adds about $102 a month over 12 months, or about $61 a month over 24 months.
Which States Cap Title Loan Interest Rates?
Among the states we serve, California, Florida, Louisiana, Oklahoma, and Virginia set yearly rate caps. Georgia and Tennessee set limits for every 30 days, while Delaware has no rate cap, and Texas doesn’t cap the fee.
Why Is My APR Higher Than My Interest Rate?
Your title loan percentage rate, or APR, includes fees as well as interest. A California loan under $5,000 with a $75 administrative fee, or a Virginia loan with a monthly fee, will show an APR above the interest rate.
Does Bad Credit Mean a Higher Title Loan Rate?
We do not run a credit check for pre-approval. If you decide to move forward with a loan, we may review credit reports from TransUnion, Equifax, LexisNexis, or FactorTrust as part of final approval.
Credit is not the main approval factor; we focus primarily on your verifiable income and vehicle equity. Applicants with bad credit are welcome to apply.
Can I Refinance a Title Loan With a High Rate?
If you have a title loan with another lender, you may be able to refinance it with us, subject to approval and state law.
Check Your Rate
Checking your pre-approval does not affect your credit score. Your free offer shows the APR, fees, payment, and term before you decide.
Applications typically take approximately 5 minutes to complete. Upon completion, a conditional approval may be given pending review of documentation. Applications approved before 2:00 PM PT on business days may be funded on the same business day.⁷
You can get your money by direct deposit or pick up cash at a MoneyGram location, with no bank account needed.
Sources
Rates and rules checked October 2026.
- California DFPI: Requirements for Consumer Loans of $2,500 to $10,000
- Federal Reserve Bank of St. Louis: Effective Federal Funds Rate
- Florida Office of Financial Regulation: Title Loan Companies
- City of Fort Worth: Credit Access Business Ordinance
- City of College Station: Credit Access Business Registration
- FTC: What To Know About Payday and Car Title Loans
- Pew Charitable Trusts: Auto Title Loans