


Yes, you may be able to get a title loan while in Chapter 13 bankruptcy, but you’ll generally need approval from your bankruptcy trustee or the court before taking on new debt.
Once that approval is in place, we review applications case by case, considering state law, your vehicle’s value, and your ability to repay alongside your existing bankruptcy plan. Because title loans are generally intended for short-term financial needs, including emergencies, you’ll also need to consider whether the additional payment fits your budget.
Before applying, speak with your bankruptcy attorney. This page provides general information, not legal advice.
Below, you’ll learn how Chapter 13 affects your ability to get a title loan, what happens if you already have one, how Chapter 13 differs from Chapter 7, and when you may be able to apply after your bankruptcy case ends.
Key Takeaways
- You’ll generally need your bankruptcy trustee’s approval before taking on a new title loan during an active Chapter 13 case.
- Applications are reviewed individually based on state law, your vehicle, and your ability to repay alongside your Chapter 13 plan.
- An existing title loan isn’t eliminated by Chapter 13. Instead, it typically becomes part of your repayment plan and may be modified by the bankruptcy court.
- After your Chapter 13 case ends, you may be able to apply for a title loan without trustee approval.
Can You Get a Title Loan While You’re in an Active Chapter 13 Case?
We may consider a new title loan application while you are in an active Chapter 13 case, but only once your bankruptcy trustee has approved you taking on new debt. Without that approval, we cannot move forward, and applying before you have it would be premature.
When we do review an application from someone in an active Chapter 13 case, we weigh the same core factors we consider for any borrower:
- State law requirements
- The condition and value of the vehicle
- Your demonstrated ability to repay
The added complexity is that your repayment plan already claims a significant portion of your income. We have to be confident that adding a new loan payment is genuinely manageable, not just technically possible.
Talk to your bankruptcy attorney before applying. Taking on new debt without the required approval could affect your bankruptcy case or repayment plan.
Why Does a Chapter 13 Trustee Control New Borrowing?
A Chapter 13 trustee is responsible for making sure your court-approved repayment plan remains realistic, because taking on new debt can affect your ability to make those payments.
What does the trustee consider?
Before approving new borrowing, the trustee may consider:
- Whether the loan fits within your court-approved repayment plan.
- Whether you can afford the additional monthly payment.
- Whether taking on new debt could affect payments to your existing creditors.
Talk to your bankruptcy attorney first
Before applying for a title loan, ask your bankruptcy attorney whether your trustee is likely to approve a secured loan. Approval practices vary by court district, and your attorney can advise you based on your specific case.
You can also refer to the U.S. Courts’ Chapter 13 Bankruptcy Basics guide for an overview of the bankruptcy process before speaking with your attorney.
What Happens to an Existing Title Loan If You File Chapter 13?
If you already have a title loan when you file Chapter 13, the loan isn’t automatically eliminated. Because it’s a secured debt backed by your vehicle, it typically becomes part of your court-approved repayment plan rather than being discharged.
Because a title loan is a secured debt, meaning the lender holds a lien on your vehicle title as collateral, you’ll generally continue repaying the loan through your Chapter 13 plan, although the terms may change.
Your Loan Terms May Change
Depending on your circumstances, your attorney may be able to:
- Negotiate a lower interest rate on the existing loan
- Reduce the loan balance to your vehicle’s fair market value, where permitted by law
- Seek the return of a recently repossessed vehicle⁵
These outcomes are not automatic. Any changes depend on your case, applicable law, and negotiations between your attorney, the bankruptcy trustee, and the lender.
If you want to learn more about repossession, see our guide on title loan repossession and how to avoid losing your car.
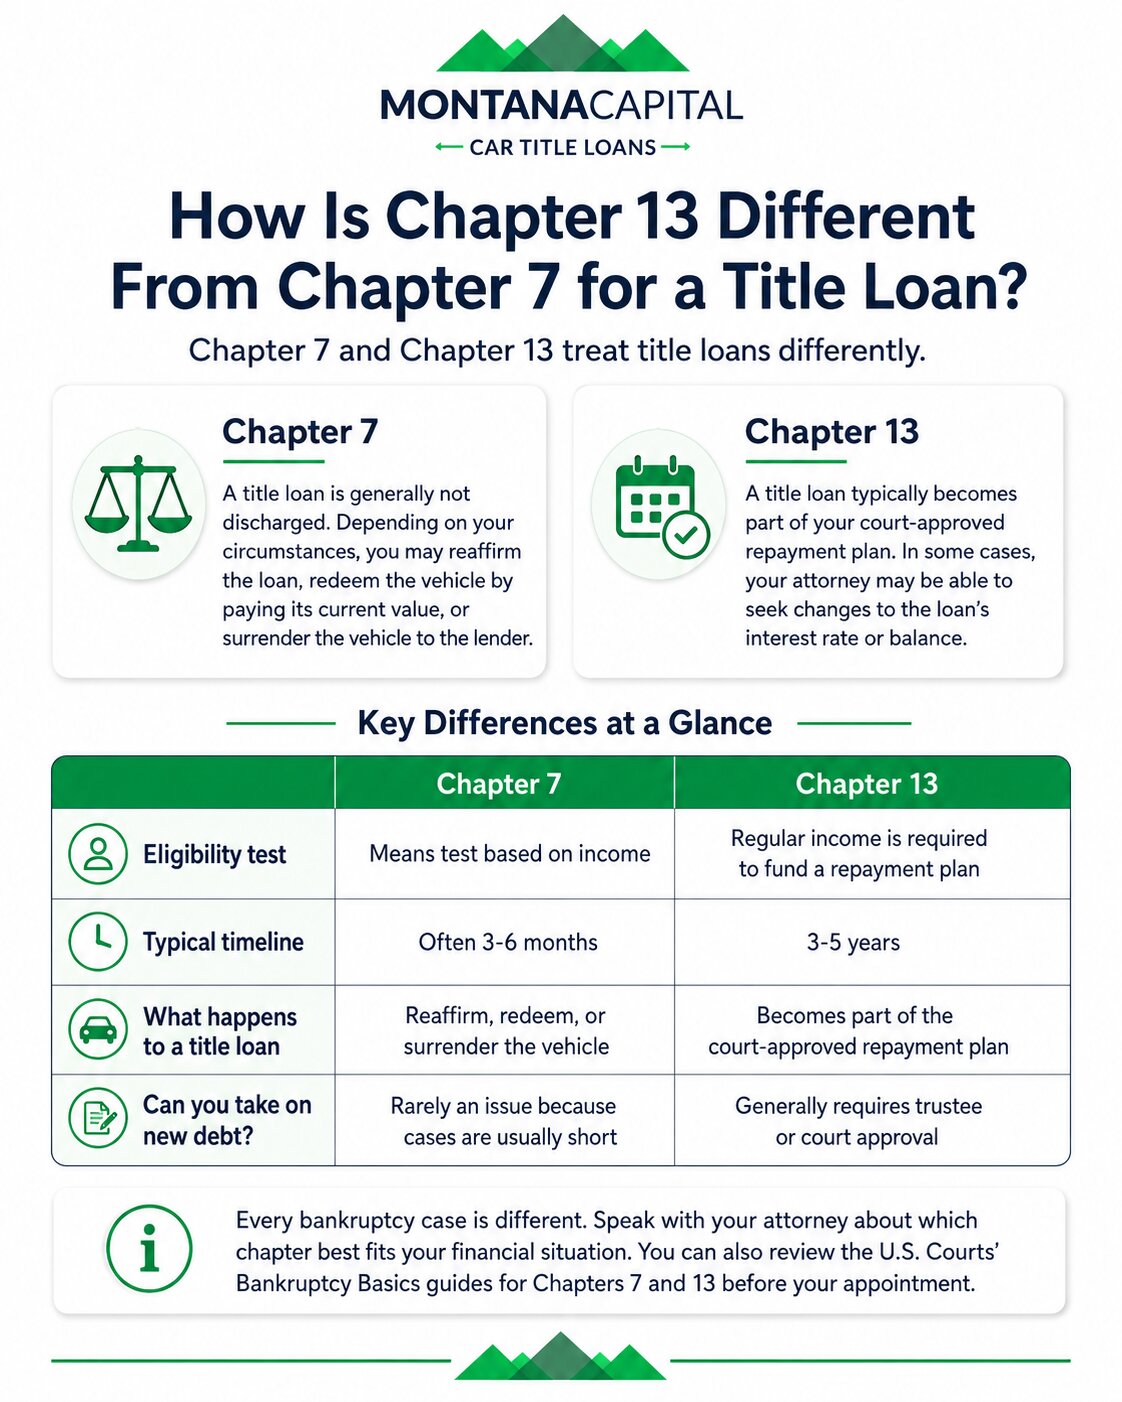
How Is Chapter 13 Different From Chapter 7 for a Title Loan?
Chapter 7 and Chapter 13 treat title loans differently:
- Chapter 7: A title loan is generally not discharged. Depending on your circumstances, you may reaffirm the loan, redeem the vehicle by paying its current value, or surrender the vehicle to the lender.
- Chapter 13: A title loan typically becomes part of your court-approved repayment plan. In some cases, your attorney may be able to seek changes to the loan’s interest rate or balance.
Can You Get a Title Loan After Your Chapter 13 Case Ends?
Once your Chapter 13 case is discharged or dismissed, you generally no longer need trustee approval to take on new debt. You may then be able to apply for a title loan based on the lender’s standard eligibility requirements.
Before applying, we encourage borrowers to understand whether a title loan is the right option. A title loan primarily for short-term emergency needs, particularly when lower-cost credit options aren’t available. It helps to have a clear picture of your current income, your monthly expenses, and a realistic plan for repayment within the loan term.
After your case closes, the ordinary approval criteria apply. We look primarily at two things: your vehicle and your ability to repay.
A lien-free vehicle title, proof of income such as a recent pay stub or documentation of steady income, and a completed application are the starting point. A credit check may be part of the review, but your credit score is not the primary approval factor.³
Having a Chapter 13 on your credit history does not automatically disqualify you. We understand that people who’ve been through bankruptcy have often faced circumstances beyond their control, and we evaluate each application on its own merits.
If you’re not sure whether your case is still open, PACER, the Public Access to Court Electronic Records system at pacer.uscourts.gov, is the most reliable way to check your own case status before you apply anywhere. Don’t assume your case is closed based on memory of a court date. Confirm it directly.
The Bottom Line
If you’re in an active Chapter 13 bankruptcy, you may still be eligible for a title loan, but you’ll generally need your bankruptcy trustee’s or the court’s approval before applying. Once that approval is in place, we review each application individually based on state law, your vehicle, and your ability to repay.
Before applying, speak with your bankruptcy attorney. Taking on new debt without the required approval could affect your bankruptcy case.
If your Chapter 13 case has been discharged or dismissed, you may be able to apply for a title loan without trustee approval. You can check your eligibility online in about five minutes, and for eligible applicants, the vehicle inspection may be completed online.
Ready to see if you qualify? Get started now or call us at 1 888 508-5366.
Important: Title loans are expensive and intended for short-term financial needs only. They may involve high fees and interest rates and are not a long-term financial solution. Consider alternatives such as personal loans, credit union loans, or borrowing from family or friends before proceeding.
Frequently Asked Questions
Do I Need My Trustee’s Permission to Get a Title Loan During Chapter 13?
Generally, yes. Taking on new debt can affect your court-approved repayment plan, so trustee or court approval is typically required. Your bankruptcy attorney can explain the requirements for your case.
What Happens to My Title Loan if I File Chapter 13?
A title loan is a secured debt, so it typically becomes part of your Chapter 13 repayment plan rather than being discharged. Depending on your case, your attorney may be able to seek changes to the loan terms through the bankruptcy process.
Are There Lenders That Work With Chapter 13 Filers?
Some lenders consider applications from borrowers in an active Chapter 13 case. We review applications individually once trustee or court approval has been obtained, but approval is generally more limited than for borrowers who are not in bankruptcy.
Can I Get a Title Loan After My Chapter 13 Is Discharged?
Generally, yes. Once your Chapter 13 case is discharged or dismissed, you generally won’t need trustee approval to take on new debt, although the lender’s standard eligibility requirements still apply.