



Yes, in some cases. A negative or overdrawn bank account isn’t the same thing as bad credit, and it doesn’t automatically rule you out of getting a title loan.
That said, a loan isn’t always the first move. Depending on how deep the hole is and why you’re in it, a few no-cost steps can sometimes fix things faster than borrowing does.
Montana Capital Car Title Loans® provides title loans, so that is the borrowing option we cover in detail here. But we will look at both sides: what you can do when your account is negative, and when a title loan may make sense as one of your options.
If your bank account is negative, you’re not alone. According to the Financial Health Network, U.S. consumers paid an estimated $12.1 billion in overdraft and insufficient-funds fees in 2024.
✓ A negative bank account means your balance has fallen below $0.
✓ Check pending transactions as well as the balance shown in your banking app before deciding how much you need.
✓ Contact your bank first. It may be able to explain a charge, waive a fee, or discuss another way to bring the account to a positive balance.
✓ Having a negative bank account does not automatically prevent you from applying for a title loan.
✓ Approved borrowers can receive funds through MoneyGram cash pickup, so a bank account is not required to receive the money.
Editorial Disclosure: Montana Capital Car Title Loans® (NMLS ID 2249848) is a licensed direct lender. This content is informational only and does not offer legal or financial advice. Terms, APRs, and availability may vary by state and borrower qualifications.
What Does a Negative Bank Account Mean?
Your account goes negative when transactions take the balance below $0.
Say you have $80 in checking and a $120 automatic payment goes through. If the bank pays it, your balance could drop to -$40 before any applicable charges are applied.
This is called an overdraft. It happens when your bank allows a payment to go through even though you don’t have enough money in your account to cover it.
There are steps you can take to bring your balance back above zero and avoid further fees.
Whether a transaction is paid, declined, or charged a fee depends on the payment type, your bank, and your account’s overdraft settings. Fees vary between banks, so it is better to check your own account terms than assume every overdraft works the same way.
The balance shown in your banking app may not tell the whole story either. Card payments, checks, or automatic bill payments may still be pending clearance.
If your bank account has a negative balance, check completed and pending transactions before working out exactly how much you need to bring it back above zero.
My Bank Account Is Negative, and I Have No Money: What Should I Do?
If you cannot clear the balance immediately, focus first on stopping the shortfall from getting bigger.
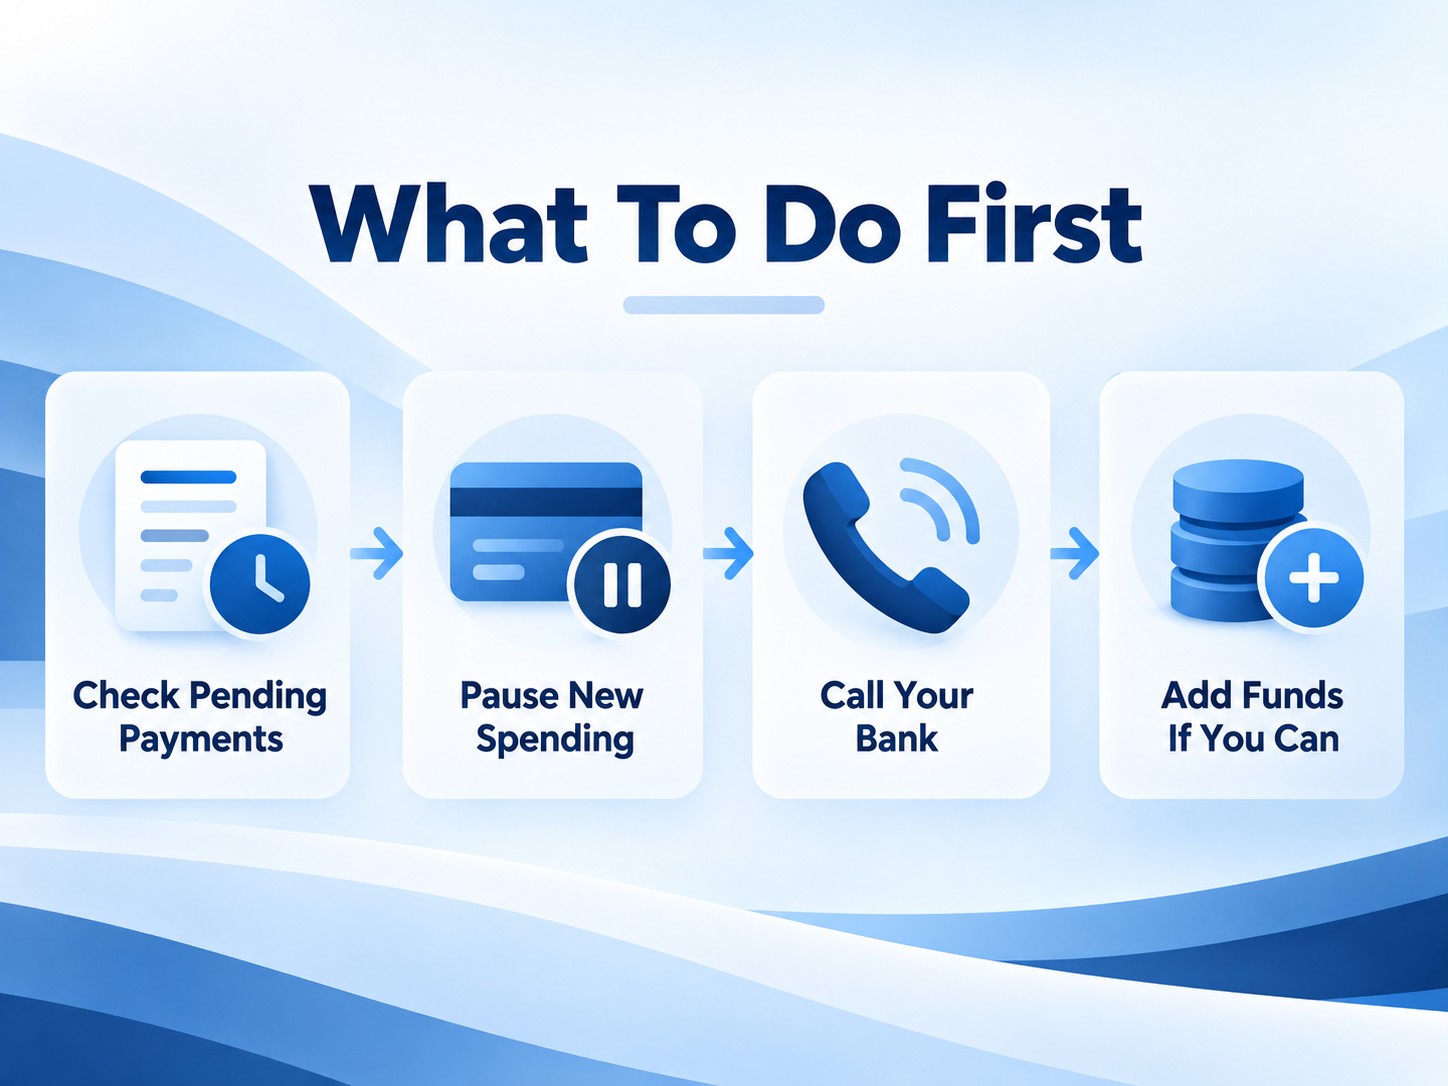
Check How Much You Really Need
Start with the negative balance, then look at anything that has not cleared yet.
If your account shows a negative $75, but another $60 automatic payment is due tomorrow, putting $75 into the account will not solve the problem for long.
Your bank can tell you which transactions are still pending and whether any further charges are due.
Pause New Spending From the Account
Avoid using the debit card or writing checks from the overdrawn account while you work out the shortfall.
Look at upcoming automatic payments too. A subscription you no longer use might be easy to cancel, while an essential bill may be better handled by calling the company and asking whether the due date can be moved.
Call Your Bank
It is worth calling even when you know exactly why the account is negative.
Ask:
- What transactions have not cleared yet?
- Are any further fees due?
- Can any fee be waived?
- Is there a deadline to bring the account to positive?
- Does the bank offer another way to deal with an overdraft?
A waiver is not guaranteed, but it is worth asking.
If something on the account looks wrong, ask the bank to explain the charge before paying it.
Put Money In If You Have Another Source
If you have accessible savings, an upcoming paycheck, or another source of money, work out whether it will cover both the current negative balance and anything still waiting to clear.
Try to leave some room rather than bringing the account back to exactly $0.
If one unusually large payment caused the problem, dealing with that single shortfall may be enough.
If your account regularly falls below zero at the same point each month, it is worth looking at the wider pattern before borrowing to cover another gap.
How an Overdrawn Bank Account Affects Your Loan Options
An overdrawn bank account can make it harder to get a loan from a bank or credit union, especially if you already owe that bank money. However, it doesn’t mean every lender will turn you down.
A lender using different approval criteria, such as a title loan company, is a different story.
With Montana Capital Car Title Loans®, a negative bank balance by itself does not prevent you from checking whether you may qualify for a car title loan.
We review your vehicle’s market value alongside your ability to repay so the loan amount is appropriate for your financial situation.
It’s still worth comparing the cost with ways of fixing the balance without taking on new debt.
Using a Title Loan With a Negative Bank Account Balance
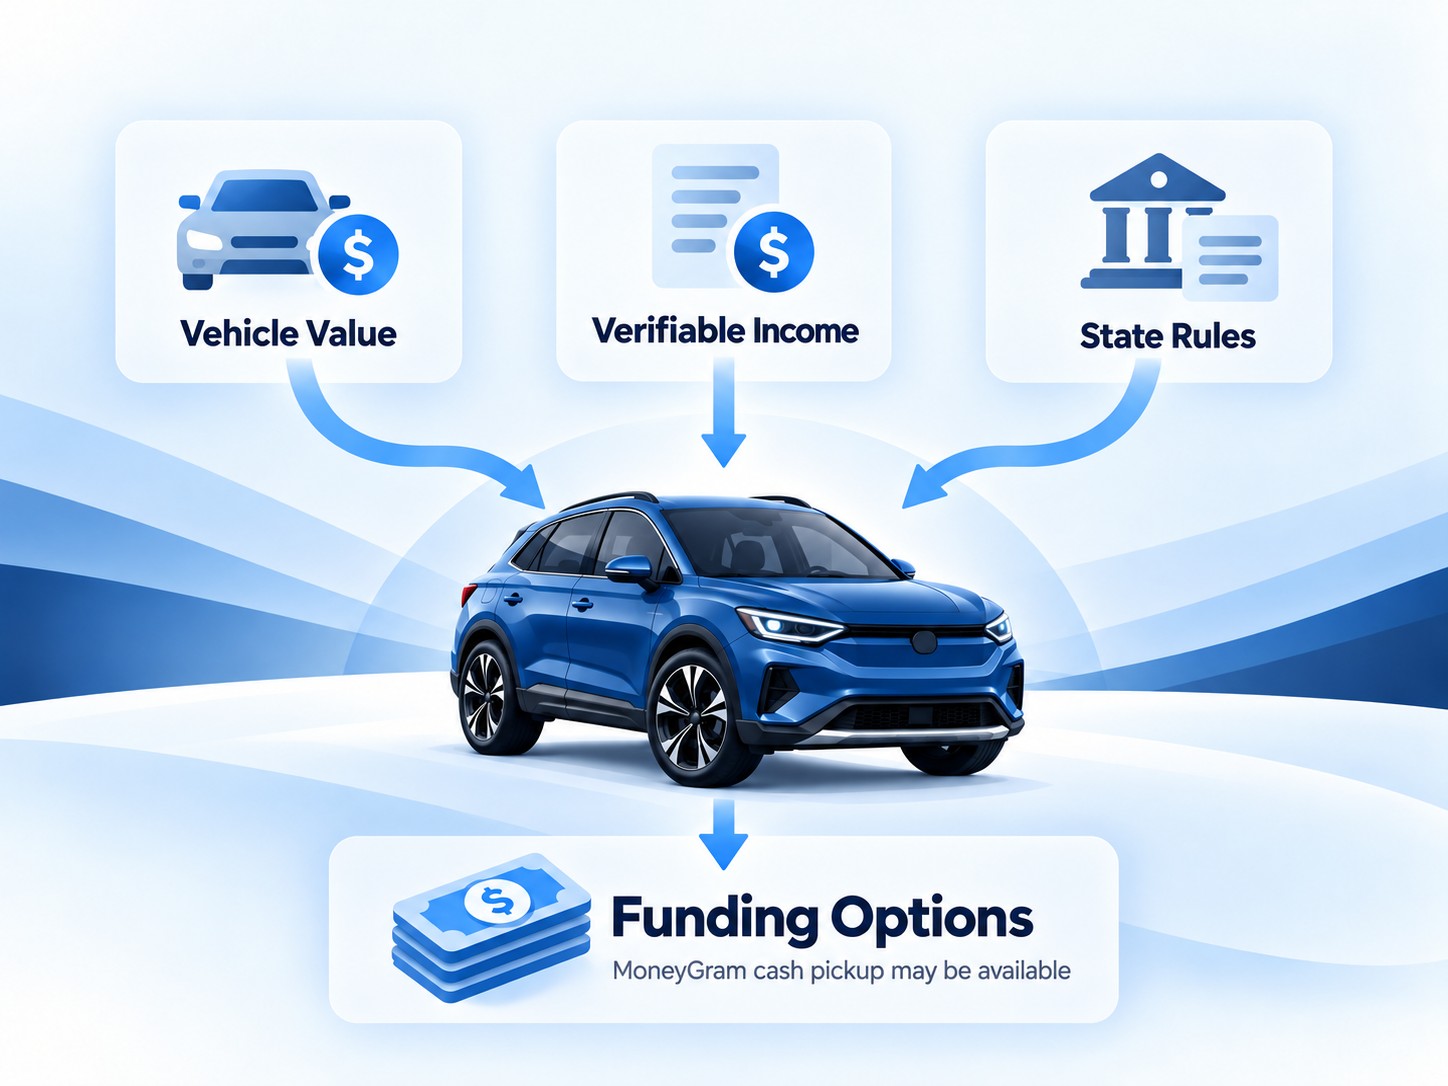
If you’re dealing with a negative balance and need cash to bring it current, the title loan option is worth understanding fully before you decide.
Our title loans range from $500 to $50,000, or a state-specific range.
Loan amounts can be up to 70% of your car’s value, based on the vehicle, your verifiable income, and state law. You are free to borrow only what you actually need rather than automatically taking the maximum amount available.
Terms can run for up to 36 months, with shorter terms where state law requires.
What We Look at When You Apply
We don’t run a credit check for pre-approval. If you decide to move forward with a loan, we may review credit reports from TransUnion, Equifax, LexisNexis, or FactorTrust as part of the final approval.
Credit is not the main approval factor; we focus primarily on your verifiable income and vehicle equity. Applicants with bad credit are welcome to apply.
Here’s what you’ll need, and why we ask for it:
- Proof of income. We ask for this because your payment has to fit your budget. A loan you can’t afford can lead to extra costs, missed payments, and the risk of losing your car.
- A lien-free title in your name, or one that’s nearly paid off. Lien-free means no other lender has a claim on your car. The car secures the loan, so the title needs to be yours.
- Interior and exterior photos of your car. These help us check its condition and value. In many cases, this means the inspection can be done online.
- A government-issued photo ID showing you’re 18 or older. This confirms who you are.
- Living in a state we serve. Your loan follows your state’s law.
Proof of insurance is required for loans over $5,000 and may sometimes be required below that amount, depending on the vehicle. You can see the full list of title loan requirements.
What Does a Title Loan Cost?
APR (annual percentage rate) shows the yearly cost of borrowing, including interest and certain fees.
Our APR is typically up to 175%, although some states have lower legal limits. Your rate also depends on how much you borrow and your ability to repay.
Where state law allows, there is a $75 processing fee and a $15 title registration fee, for a total of $90. There is no prepayment penalty.
Your car secures the loan. If you don’t repay, you could lose your car. Title loans can be expensive, so they’re best kept for real emergencies when lower-cost credit isn’t available to you.
What If Your Bank Account Is Already Overdrawn?
Funding does not have to be sent into the account that is already negative.
If the loan is deposited into an overdrawn account, your bank will usually use it to cover the negative balance and fees first. If you need the money for rent or another bill, cash pickup at MoneyGram or a deposit to a card can keep it separate.
You can pick up your cash at a MoneyGram location, so you may be able to get a title loan without a bank account if you otherwise qualify.
That can also be useful if you simply do not have a bank account available for direct deposit.
If you are comparing the amount you need with what repayment could look like, our Title Loan Calculator can show you how different loan amounts and terms affect the numbers.
Before Borrowing to Cover an Overdraft
It can be tempting to borrow the full amount you qualify for, especially when other bills are waiting. That does not mean you should.
Start with what is actually needed to bring the account current. Include payments you already know are about to clear, but avoid borrowing extra simply because it is available.
Then look beyond today’s overdraft.
If covering a $400 negative balance creates a new loan payment that leaves you short again next month, the underlying problem has not really gone away.
Compare the APR, fees, payment, and total repayment with the other choices available to you. A bank arrangement, a moved bill date, or money from another source could cost less.
If those options are not available and you do decide to borrow, knowing the full cost before signing gives you a much better basis for deciding whether the loan fits your budget.
Other Ways to Deal With a Negative Balance
A title loan isn’t the only option, and if the shortfall is small, another approach may solve it without taking on new debt at all.
Ask your bank what it can do. A fee waiver or another arrangement may reduce the amount you need to find.
Talk to whoever is due to take a payment. A utility provider, landlord, or other creditor may agree to move a due date or arrange payments rather than attempting another withdrawal from an empty account.
Ask family or friends. If that is realistic for you, it may give you a way to clear a small shortfall without interest. Be clear about when and how the money will be repaid.
Sell something you no longer need. Electronics, furniture, or other unused items may be enough to cover a relatively small gap.
Pick up some extra income. A part-time shift, freelance work, delivery work, tutoring, or pet sitting may help if you have some time to deal with the shortfall.
Compare other borrowing options. A credit union or unsecured personal loan may cost less if you qualify, depending on the terms you are offered.
Talk to a nonprofit credit counselor. If the negative balance is part of a wider pattern rather than a one-time problem, a nonprofit counselor can look at the bigger picture before you take on anything new.
What Happens If You Leave Your Bank Account Negative?
Leaving a negative bank balance unresolved can eventually create a bigger problem.
Depending on your bank’s policies, transactions may be restricted, and the account may eventually be closed.
If an account is closed while you still owe money, the unpaid balance may be reported to a specialist checking-account reporting company such as ChexSystems or Early Warning Services.
Banks and credit unions can use those reports when deciding whether to open another account for you, so leaving an unpaid negative balance can make opening a new checking account harder.
Checking-account history is generally separate from the traditional credit reports produced by Experian, Equifax, and TransUnion. However, an unpaid balance that later goes to collections can create a separate credit issue.
The sooner you speak to the bank and work out what you owe, the more options you are likely to have.
How to Prevent Your Bank Account from Going Negative Again
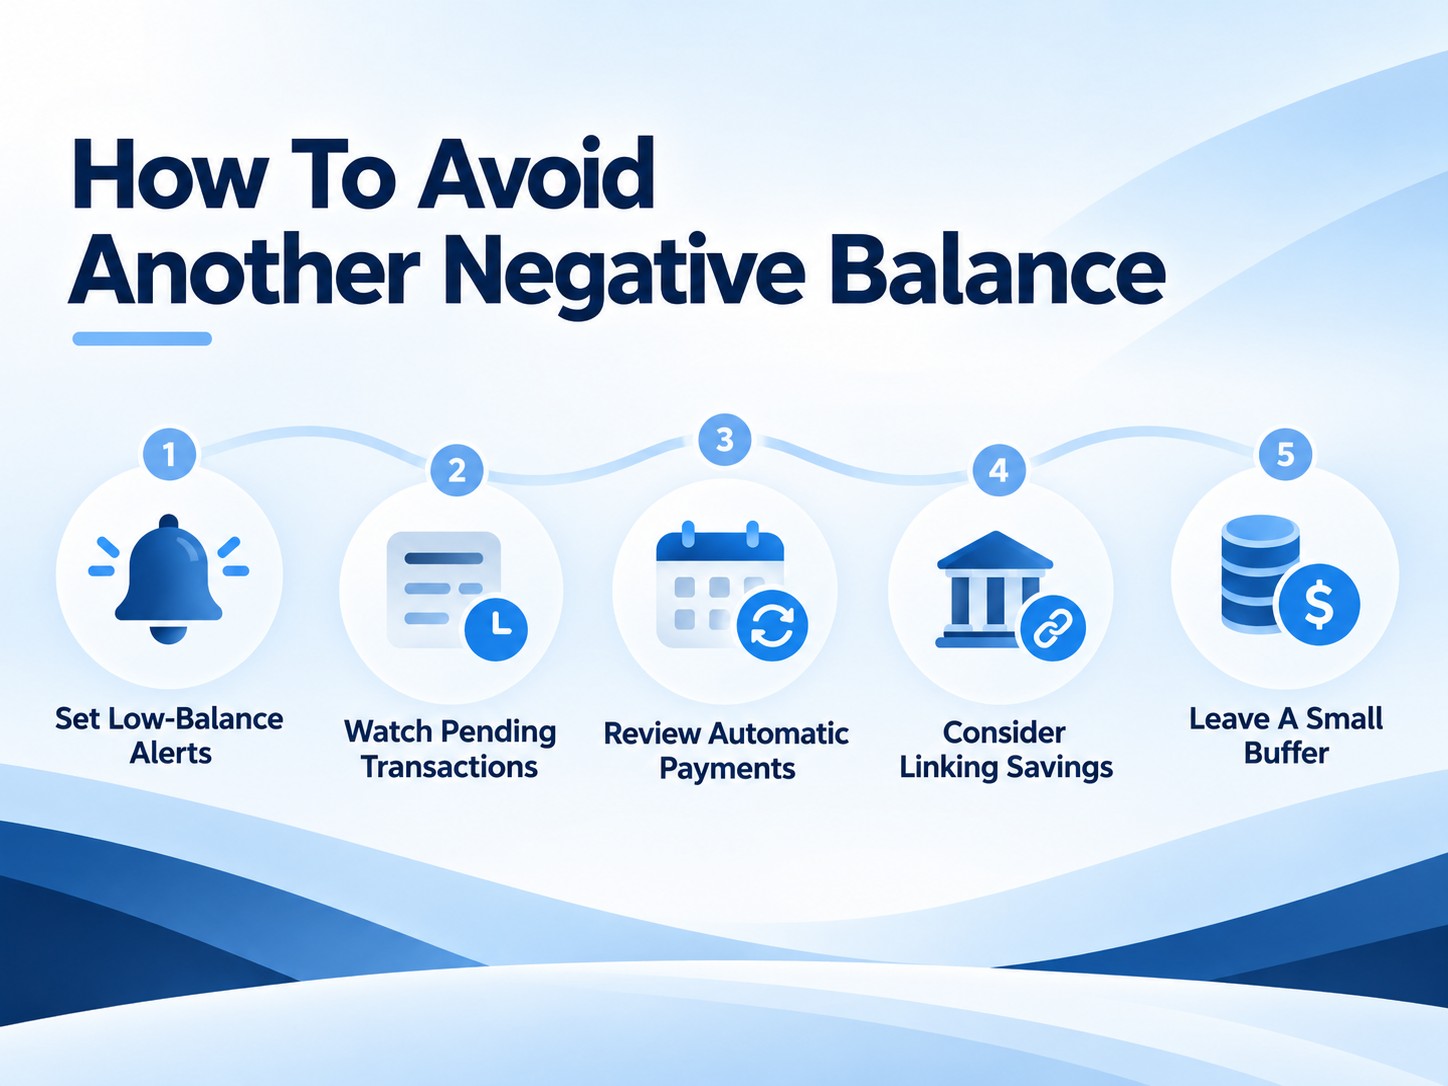
Once the balance is back above zero, work out what caused the overdraft in the first place.
A forgotten subscription needs a different fix from an account that runs short at the same point every month.
Set a Low-Balance Alert
Most banking apps allow you to choose a balance that triggers a notification.
Do not wait until the account reaches zero. A warning at $100, $200 or another level that works for you gives you time to check what is still due.
Watch Pending Transactions
The headline balance in your app does not always tell you what is about to leave the account.
Check pending card payments, outstanding checks, and automatic payments as well.
Review Automatic Payments
Subscriptions and recurring charges are easy to forget because you don’t actively make the payment each month.
Look through recent transactions and cancel services you no longer use.
For bills you need to keep, see whether the payment date can be moved closer to payday if the current timing regularly causes problems.
Review Your Overdraft Settings
Check what happens if you try to make a payment without enough money available.
For ATM withdrawals and one-time debit card purchases, federal rules generally require you to opt into overdraft coverage before a bank can charge an overdraft fee for paying those transactions.
Checks and recurring electronic payments work differently.
If you are not sure what you agreed to, ask your bank.
Consider Linking Savings
Some banks let you link a checking account to a savings account so money can be transferred if the checking balance runs short.
There may still be a transfer fee, so check what your bank charges before setting it up.
Leave a Small Buffer Where You Can
If your budget allows it, try not to treat the final few dollars in checking as money available to spend.
Even a small cushion can cover a forgotten subscription or a payment that clears earlier than expected.
FAQ
Does a Negative Bank Balance Affect Loan Approval?
It can, depending on the lender and the type of loan.
Different lenders use different approval criteria. With Montana Capital Car Title Loans®, a negative bank balance alone does not automatically disqualify you. We focus primarily on your verifiable income and vehicle equity when reviewing a title loan application.
How Much Should I Borrow to Cover an Overdrawn Account?
Start with the amount required to bring the account to a positive balance, including any pending payments you already know are due.
Do not automatically borrow the maximum available. Look at the payment and total repayment as well, and make sure taking on the loan will not simply leave you short again next month.
Can I Get a Loan With Bad Credit and an Overdrawn Bank Account?
You may still be able to apply for a title loan.
Bad credit does not automatically rule you out at Montana Capital Car Title Loans®. Credit reports may be reviewed as part of final approval, but credit is not the primary approval factor.
Can I Use a Title Loan to Pay Off an Overdraft?
Yes. Title loan proceeds can be used to cover a negative checking balance.
Before borrowing, compare the cost of the loan with alternatives such as speaking to your bank, moving a bill date, or using another source of funds. Your car secures the loan, so you should be confident that the repayments fit your budget before proceeding.
Bringing Your Account Back to Positive
A negative bank account is common, fixable, and not a sign you’ve run out of options.
Small shortfalls are often best solved without new debt, whether that means selling something, picking up some extra income, or simply having a conversation with your bank.
When the gap is bigger, and you need access to cash, a title loan is one option to compare if you own a qualifying vehicle and can afford the repayments.
If that is the route you decide to explore, start with the amount you actually need rather than the maximum available.
Checking your pre-approval does not affect your credit score, and you can review the terms offered before deciding whether to continue.